Pensions and Inheritance Tax
About pensions and inheritance tax
Pensions and Inheritance Tax used to be separate subjects. This is not the case any more, following announcements in the Autumn Budget of 2024. From 6th April 2027, pensions will be included in Inheritance Tax calculations. For many people, this will be enough to push estates into Inheritance Tax, possibly resulting in significantly greater tax for your family.
The problem can be neatly summed up: before 6th April 2027 pensions are free from Inheritance Tax. After this date, Inheritance tax could eat your pension at 40% (and greater in certain situations).
This page examines pensions and Inheritance Tax, explaining the changes that are happening, what you should consider doing to avoid this tax, with worked examples to illustrate the issues.
1. Inheritance Tax principles
Before you can consider the impact of pensions and inheritance tax, it is useful to understand basic principles of inheritance tax. You can view our comprehensive resource on 7 strategies to avoid inheritance tax. This explores inheritance tax in much greater detail.
Calculating the estate
When a UK-resident person dies, their worldwide estate is calculated. Your estate is the value of all of your assets, less any outstanding liabilities. Inheritance tax is payable on assets above the standard available allowances. Some assets are not included in your estate, and until 5th April 2027, pension plans are excluded from inheritance tax calculations.
Naturally, the concern arising from the changes to inheritance tax rules for pensions from April 2027 is that the value of pensions will increase a person’s estate. In turn, more inheritance tax could be due, and even more if affected by the taper tax trap.
The Nil Rate Band
Every individual has a tax-free allowance, worth £325,000, known as the Nil Rate Band. Any part of an estate above this threshold is generally taxed at 40%.
The Residential Nil Rate Band
An additional allowance applies, worth up to £175,000, known as the residence nil rate band. This applies when a main home is left to direct descendants (such as children, stepchildren, and grandchildren). Combined with the Nil Rate Band, an individual can potentially pass on up to £500,000 tax-free.
Spouse exemption
Transfers between spouses are generally free of inheritance tax. The first to die can pass any remaining Nil Rate Band and Residential Nil Rate Band to their surviving spouse. This means that often a couple pays no inheritance tax on first death. Instead, the allowances can combine to a total of £1 million, which reduces the taxable estate on second death.
The Taper Trap over £2 million
When your estate reaches £2 million, the Residential Nil Rate Band is gradually removed at a rate of £1 for every £2 of assets over this limit. This means that when an estate reaches £2,350,000, the residential nil rate band is removed.
Fiscal drag on inheritance tax allowances
The Nil Rate Band has not increased since April 2009 and is now frozen until at least April 2031.
The Residential Nil Rate Band is also frozen. It has been at £175,000 since 2020 and will remain unchanged until April 2031.
2. Pensions and inheritance tax – summary of the position before 6th April 2027
Before 6th April 2027, defined contribution pension death benefits are usually free from Inheritance Tax. Pension plans are a fantastic way to shelter money from tax while you are alive. Pensions can continue after your death and this means that they have become one of the best ways of avoiding Inheritance Tax. These rules still exist, but are changing. To be fair to the Government, this Inheritance Tax impact was never intended when pensions were created; this position has evolved due to a number of tax reforms over the last 10-15 years. Read more about pensions and Inheritance Tax.
For most defined contribution pensions, death benefits are usually paid to nominated beneficiaries following an expression of wishes nomination, which is completed by the member of the pension plan. After the member dies, this nomination is almost always followed by the pension scheme. The current rules generally mean that pension death benefits are passed free from Inheritance Tax. Please bear in mind that this is general guidance and will be different, depending on the situation.
Death before age 75
If the pension scheme member dies before age 75, then pension lump sum up to £1,073,100, or income payments can be made to anyone completely tax-free (including inheritance tax), provided that the death benefits are paid within 2 years of the member’s death.
Death from age 75
If the pension scheme member dies after they reach age 75, then any pension death benefits are counted in the recipient’s income for that tax year, if they are withdrawn from the pension scheme. Therefore, the recipient will be liable to income tax between 0% and 45%, depending on the amount, and their individual tax position. However, no inheritance tax is payable on this transaction.
Options for beneficiaries receiving pension benefits
The options available to beneficiaries of a pension scheme where the member has died depends on the scheme rules as well as general pension rules. This means that not every pension plan offers these options.
Lump sum
The pension fund is paid as a lump sum to the beneficiaries. If the member died before age 75, no income tax is payable unless the total lump sum benefits exceed £1,073,100; no Inheritance tax is payable. If the member dies from age 75, income tax is charged on income taken, based on the beneficiary’s marginal tax rate.
Annuity
The pension fund is paid as a guaranteed income for life to the beneficiaries. If the member died before age 75, no income tax is payable and no Inheritance tax is payable. If the member dies from age 75, income tax is charged on income taken, based on the beneficiary’s marginal tax rate.
Beneficiary Drawdown
The pension fund passes to a new pension scheme in the name of the beneficiary. This grows in a tax-free environment until income is taken. If the original member died before age 75, no Inheritance tax is payable on the transfer from one pension to another. No income tax is payable on the future income from this scheme where the member died before age 75. If the member dies having reached age 75, income tax is charged on income taken by the successor, based on the recipient’s marginal tax rate.
It is possible to nominate a beneficiary to receive your pension benefits and this person can inherit your pension without paying inheritance tax. This has created a system where families can pass down capital to future generations while avoiding inheritance tax. In theory, those future generations could also pass on this wealth free of inheritance tax. The only future tax would be income tax paid by beneficiaries who receive post-75 death benefits.
Recipients of beneficiary drawdown can opt for lump sum payments or switch to an annuity.
General inheritance tax planning with pensions prior to 6th April 2027
The ability to avoid inheritance tax using pensions and transfer wealth through generations is extremely powerful. When we add this to the other tax benefits of pension plans, it is usually the case that we reserve pension plans to last when taking withdrawals to fund lifestyle costs.
Typically, we suggest spending in this order:
- Taxable assets (savings, investments)
- Tax-free investments and savings (ISAs and premium bonds)
- Pensions
The actual withdrawal order will depend on a variety of factors and so could change.
Summary tax on pensions after death prior to 6th April 2027
| Death | Inheritance tax | Income tax |
| Before age 75 | No | No, unless lump sums exceed £1,073,100 |
| From age 75 | No | Yes on withdrawals or income at recipient’s marginal rate |
3. Pensions and Inheritance Tax after 6th April 2027 – what is changing?
After 6th April 2027, defined contribution pension death benefits will be subject to Inheritance Tax just like other assets, such as property or investments. This will come as a blow to many who planned their inheritance around the rules that permitted inter-generational transfer of pension assets. Added to that, in the worst circumstances, future beneficiaries could suffer a triple attack on these pensions:
- Inheritance tax at 40%
- Reduction of the estate’s residential nil rate band
- Income tax on withdrawal from the pension on the beneficiaries
If an estate pays 40% inheritance tax on a pension plan then the beneficiary pays income tax on the remaining pension that passes to them, this person might get at little as 33% of the value of the pension at death.
Death before age 75 from 6th April 2026
If the pension scheme member dies before age 75, after 6th April 2027, inheritance tax will now apply. However, the beneficiaries will not pay income tax, unless the lump sums received exceed £1,073,100. Anything above that amount will be taxed at the beneficiary’s marginal income tax rate.
Death from age 75 from 6th April 2026
If the pension scheme member dies after they reach age 75, after 6th April 2027, inheritance tax will now apply. In addition, the beneficiaries could pay income tax on top of the inheritance tax paid by the estate (assuming they withdraw the pension money from the scheme).
Any pension death benefits are only counted in the recipient’s income for that tax year, if they are withdrawn from the pension scheme. Therefore, the recipient will be liable to income tax between 0% and 45%, depending on the amount, and their individual tax position. The amount liable to income tax is calculated after deduction of the inheritance tax due as a proportion of the whole estate, applied to that pension plan. This may be complicated, so we have provided some practical guidance below.
Options for beneficiaries receiving pension benefits
The options available to beneficiaries of a pension scheme where the member has died depends on the scheme rules as well as general pension rules. This means that not every pension plan offers these options. For example, some older schemes may only pay the pension death benefits as a lump sum, meaning automatic application of inheritance tax to the estate and income tax on the beneficiaries. This change has significantly undermined the intergenerational transfer of wealth that would previously have been possible.
Lump sum
The pension fund is paid as a lump sum to the beneficiaries. If the member died before reaching age 75, no income tax is payable but Inheritance tax could be payable. If the member dies having reached age 75, income tax is charged on income taken, after deduction of inheritance tax, based on the beneficiary’s marginal tax rate. This means that the lump sum received will be lower due to the additional inheritance tax.
The lump sum option is the default for most schemes and is attractive to beneficiaries who want unfettered access to their inheritance. The downside is that this is likely to be the highest tax cost. In the worst-case scenario, the total tax could reach 67%.
The diagram below shows the tax position before and after the changes to inheritance tax for pensions, assuming the lump sum option is taken by a beneficiary who pays income tax at 40%, and the total is less than £1,073,100.

Annuity
The pension fund is paid as a guaranteed income for life to the beneficiaries. If the member died before reaching age 75, no income tax is payable but Inheritance tax could be payable. If the member dies having reached age 75, income tax is charged on income taken, after deduction of inheritance tax, based on the beneficiary’s marginal tax rate. This means that the annuity income will be lower due to the additional inheritance tax.
The annuity option is attractive to beneficiaries who want to receive a guaranteed income for life. It is not often the route taken as it offers less future flexibility.
Beneficiary Drawdown
The pension fund passes to a new pension scheme in the name of the beneficiary. Again, inheritance tax could be payable. The new drawdown pension will be lower if inheritance tax is due. It then grows in a tax-free environment until later income is taken. If the original member died before reaching age 75, no income tax is payable on the future income but the income that could be paid would be diminished because of the inheritance tax payable. If the member dies having reached age 75, income tax is charged on income taken, based on the beneficiary’s marginal tax rate, and this would also be affected by the reduction in the capital value due to the inheritance tax payable.
The beneficiary drawdown option is probably the best for most people, provided they do not want instant access to the inherited pension capital. If a beneficiary does not need an income at the outset, they can retain the inherited pension until they need a future income. This could be in stages, as a lump sum, or even the annuity. The beneficiary drawdown cannot help you to avoid inheritance tax, but it can be a more tax-efficient way to save income tax in the future.
The diagram below shows the tax position before and after the changes to inheritance tax for pensions, assuming the beneficiary drawdown option is selected by a beneficiary who pays income tax at 40%. The arrows show the income tax that could be avoided, or postponed, retaining capital in a tax-free beneficiary drawdown pension plan.

General inheritance tax planning with pensions after 6th April 2027
The decision whether to use pension plans for income during your lifetime has now changed, due to the impact on inheritance tax paid by pensions. However, it is not straightforward to apply a new approach to existing pension plans, when considering whether to take income during your lifetime. The main reason is the income tax that you will pay if you withdraw from your pension. The decision will depend on a variety of factors, including your other assets and income tax position.
Summary tax on pensions after death from 6th April 2027
| Death | Inheritance tax | Income tax |
| Before age 75 | Yes | No, unless lump sums exceed £1,073,100 |
| From age 75 | Yes | Yes on withdrawals or income at recipient’s marginal rate |
4. Pensions and inheritance tax before and after April 2027
As mentioned above, your pension plans should now come into your thinking when planning for inheritance tax. Your estate may not currently pay inheritance tax and your pension plans could suddenly mean that tax is payable. Alternatively, your pensions could dramatically increase the inheritance tax due.
A worked example of the impact of pensions on inheritance tax after April 2027
Emily is not married and has the following estate:
- House worth £500,000
- Investments worth £200,000
- Pension plan worth £300,000
If Emily leaves her house and other assets to her children, her estate qualifies for the nil rate band and residential nil rate band. Her taxable estate before April 2027 is £700,000. Her inheritance tax allowances come to £500,000, meaning that £200,000 is taxable for inheritance tax at 40%. Therefore, Emily’s estate would pay £80,000 in inheritance tax were she to die before 6th April 2027.
From 6th April 2027, Emily’s estate must include her pensions. This beings the total estate to £1,000,000. Deducting the allowances worth £500,000 means that £500,000 is taxable at 40%. Emily’s estate pays inheritance tax of £200,000, an increase of 150%.
Possible impact of pensions on the inheritance tax taper
Andrew is not married and has the following estate:
- House worth £800,000
- Investments worth £600,000
- Pension plan worth £800,000
If Andrew leaves his house and other assets to his children, his estate qualifies for the nil rate band and residential nil rate band. His taxable estate before April 2027 is £1,400,000. His inheritance tax allowances come to £500,000, meaning that £900,000 is taxable for inheritance tax at 40%. Therefore, Andrews’s estate would pay £360,000 in inheritance tax were he to die before 6th April 2027.
From 6th April 2027, Andrew’s estate must include his pensions. This beings the total estate to £2,200,000. Importantly, this takes Andrew’s estate over the £2 million threshold at which he begins to lose the residential nil rate band. His allowance now reduces by £100,000 to £75,000, meaning that extra inheritance tax will become due. Deducting the allowances worth £400,000 means that £1,800,000 is taxable at 40%. Andrew’s estate pays inheritance tax of £720,000, an increase of 100%. The impact of the tapered residential nil rate band means that Andrew’s estate would be taxed by an extra £40,000 than it would have been otherwise.
5. Practical issues with the new pension inheritance tax rules
What happens if a person dies before 6th April 2027 but benefits are paid after this date?
The date of death is important. The new rules on pensions and inheritance tax only apply for deaths from 6th April 2027 onwards. If someone dies before this date, the old rules apply, even if assets transfer later.
Which pension schemes are excluded from inheritance tax?
The following pension benefits are not counted for inheritance tax under the new rules:
- Dependants’ scheme pensions
- Trivial commutation lump sum benefit
- Joint life annuities from an earlier purchase
- Death in service benefits where the member was employed at the date of death
Which beneficiaries are exempt?
Spouses and civil partners are exempt from inheritance tax where they receive assets in their partner’s estate. Therefore, pensions that pass to your spouse are free from inheritance tax under the new rules. Of course, the survivor’s pensions will be subject to inheritance tax at a later date.
How is inheritance tax calculated?
The total estate is calculated by the personal representatives of the deceased. The only difference after 6th April 2027 will be that pension schemes are included in this inheritance tax calculation.
The result probably means more inheritance tax for larger estates, and some estates will have to pay inheritance tax where none was previously due. The pension scheme administrators will be responsible for providing the values of pension benefits at the date of death to the personal representatives.
Who is responsible for paying inheritance tax due on pension schemes?
The personal representatives of the deceased are responsible for calculating, reporting and paying any inheritance tax due on a pension scheme. This is usually payable within 6 months of the date of death. Interest is payable from the end of the 6th month after the date of the death.
Can the pension scheme pay inheritance tax that is due?
Yes, after 6th April 2027, this will be possible from UK pension schemes. Personal representatives of the estate can issue a payment notice to the pension scheme, which must pay the inheritance tax due within 35 days.
Certain rules apply:
- There must be sufficient funds in the pension
- The amount is at least £1,000
- The amount cannot exceed the liability of the estate for that pension scheme
This last point is important since the personal representatives can use other assets to pay pension scheme inheritance tax, but not the other way around. The estate cannot pay all the inheritance tax from one pension for example.
How does income tax work after inheritance tax is paid?
Any income tax due on benefits paid to a beneficiary is reduced by the inheritance tax due on the pension scheme affected. This amount applies whether or not the pension scheme actually pay the inheritance tax due as a result of those assets. Therefore, it could be the case that the estate pays inheritance tax from non-pension assets, meaning that the pension plan does not reduce due to inheritance tax. Even so, the income tax portion would only apply on the pension plan that passes to beneficiaries after allowing for the inheritance tax that would have been due.
For example: Sandra dies leaving a pension scheme worth £100,000. The estate calculates inheritance tax due of £40,000. The estate can apply for the pension scheme to pay £40,000 inheritance tax or to pay this from other, non-pension assets. The pension passes to Mary. If Mary takes taxable income from the pension, she will only pay income tax on the remaining £60,000, even if she receives £100,000 from the pension.
This shows that personal representatives and beneficiaries will need to keep careful records of pensions affected by inheritance tax.
Can other inheritance tax allowances apply to pensions affected?
Pension assets cannot qualify for other exemptions such as agricultural relief or business relief, even if they would have done otherwise.
Inheritance tax and the Lump Sum Death Benefit Allowance
Certain lump sum death benefit payments on death of the member before age 75 have to be counted against this allowance. If the Lump Sum Death Benefit Allowance is exceeded this means additional income tax is payable by the recipient of the benefit.
If the Lump Sum Death Benefit Allowance of £1,073,100 is exceeded then the recipient will pay additional income tax at their marginal tax rate.
The allowance applies to lump sum payments, not beneficiary drawdown or annuity income.
Importantly, if inheritance tax apples to a pension scheme on death, this should be deducted before calculating the impact on the Lump Sum Death Benefit Allowance. Therefore, the inheritance tax paid by the scheme will reduce the lump sum paid to the beneficiary and this would reduce the income tax paid on that payment. This is another reason why beneficiary or successor drawdown is likely to be a more favourable option.
The spouse exemption for inheritance tax does not rule out a tax charge for exceeding the Lump Sum Death Benefit Allowance
Location of the HMRC final rules on inheritance tax with pensions
You can find the pensions inheritance tax HMRC technical notes here.
6. The potential impact on beneficiaries
The changes to inheritance tax for pensions from 6th April 2027 could have a huge impact on beneficiaries in the worst circumstances. This could mean tax payable at more than 80% of the pension fund in the worst-case scenario.
The interaction between inheritance tax and income tax
When a pension passes to a beneficiary they have the option of taking a lump sum payment. As mentioned above, for death of the member before 75, this is free of income tax, provided this does not exceed the Lump Sum Death Benefit Allowance; from age 75 onwards, this payment is taxable on the beneficiary at the rate they pay. The lump sum paid will be added to the beneficiary’s income for that tax year, and taxed according to normal income tax rates. This means that a pension lump sum inherited for deaths after 6th April 2027 could be taxed on the beneficiary at 0%, 20%, 40% or 45%.
In fact some older pensions enforce the lump sum death benefit option, which could make this situation worse.
Step 1 – deduct the inheritance tax
The pension will deduct inheritance tax according to the value of the estate. This will reduce the amount of the pension plan liable to income tax on the beneficiary, regardless of whether the pension plan is actually used to pay the inheritance tax.
Step 2 – deduct income tax from the remaining fund
The remaining pension fund after inheritance is then used to calculate the impact of income tax on the beneficiary. If the death of the member occurred before they reached age 75, the payment must be checked against the Lump Sum Death Benefit Allowance and further income tax may be payable. For death of the member from age 75, income tax is payable according to the position of the beneficiary.
A worked example of the interaction between inheritance tax on pensions and income tax
Raj has a total estate worth £1.5 million, including £1 million in his pension. His estate qualifies for the nil rate band and residential nil rate band when he dies, aged 75. Therefore, prior to 6th April 2027 his estate would have been free of inheritance tax. After this date, his pension attracts inheritance tax worth £400,000.
The remaining pension fund is worth £600,000 after inheritance tax is deducted. Raj’s son wants to take the entire pension as a lump sum. This means that £600,000 is added to his income for the tax year in which the lump sum is paid. Even if The beneficiary has no other income in that tax year, the minimum income tax would be £253,689. If the beneficiary has their own income for the tax year, the tax would be greater. This tax is worse because the large lump sum paid would mean that the beneficiary loses their income tax personal allowance.
The total tax paid is £400,000 plus £253,689. This comes to over 65% of Raj’s pension. meaning his heir gets less than 35% of the pension pot as a lump sum payment.
The Lump Sum Death Benefit Allowance (LSDBA) and inheritance tax
There is a separate issue for death benefits in pensions, relating to the Lump Sum Death Benefits Allowance. This is a separate set of rules, which exists outside of inheritance tax, but that could mean even more tax becomes due.
- Inheritance tax looks at whether the value of unused pension funds should be in the member’s estate for tax purposes;
- The Lump Sum Death Benefits Allowance looks at whether a death lump sum can be paid tax-free to a beneficiary.
There is no offset between the 2 issues if they cross over.
The LSDBA is an allowance for tax-free benefits. It applies to death before age 75 on pension benefits paid as a lump sum. Annual income is not taxed in the same way.
For example, Stuart has a taxable estate worth £2 million but has used his nil rate band and residential nil rate band. The pension plan is worth £1 million. This means that his inheritance tax would be £800,000. If the pension is paid as a lump sum benefit on Stuart’s death, the pension value would have to be deducted from the LSDBA. If this had previously been used then the pension would have to be taxed as income on the beneficiary.
Using flexible death benefits to reduce income tax for the beneficiary
The good news is that there is a better method than the worst-case listed above. Inheritance tax will be due on pensions after 6th April 2027 regardless. Pension death benefits can be paid as a lump sum, but also as an annuity or a successor drawdown plan. The successor drawdown plan allows the beneficiary to retain the pension of the deceased in their own name, after payment of inheritance tax due on the estate. The plan would grow free of tax until a later date when the beneficiary takes a withdrawal. This could be the entire fund, or a portion of it. This allows the beneficiary to control when they pay income tax, although they would not be able to avoid the inheritance tax due.
Importantly, the estate’s personal representatives can choose which assets pay the inheritance tax, even if the pension does not actually bear this cost. If so, the pension could remain untouched by inheritance tax, although the tax would still apply, just paid from another source. There may be legitimate tax-saving reasons to take this option.
The key is to check that your pension allows for death benefits to be paid as a successor drawdown. Importantly, the beneficiaries must be named to be able to receive the benefits in this way, but some schemes will be forced to pay benefits as a lump sum, resulting in greater income tax. Many older schemes will not have flexibility built in and would only pay the inheritance as a lump sum. If this were the case, the beneficiaries will not have the flexibility to taken income as they see fit.
7. Saving inheritance tax due on pensions
If your pension plan now attracts inheritance tax, does this mean you should change your plans? Various methods for saving inheritance tax on pensions are being discussed online. The truth is that you should pay attention to the pension plans now that they form part of your estate for inheritance tax. However, it is rarely a simple case of just doing something with the pension. The reality is that the whole estate should be considered, with the pensions being one asset that has its own tax consequences.
The main strategies to save inheritance tax still work with pensions, but the environment is more complicated. Often you can use pensions to save inheritance tax, but possibly at the expense of the pensioner during their lifetime. You may save inheritance tax for your heirs only by paying income tax on the pension withdrawals during your lifetime.
Read more about saving inheritance tax in our comprehensive guide: 7 strategies to avoid inheritance tax.
When inheritance tax planning using pensions is not appropriate
Many people will be rightly concerned about inheritance tax in pensions due to the changes. However, there are some cases where inheritance tax planning is not necessary or desirable:
- Retirement security would be compromised
You should never engage in inheritance tax planning at the expense of your own financial security. - Total estate is below the inheritance tax thresholds
For example, where the estate is valued at less than £1 million for a married couple. - Likely death before age 75
The income tax-free benefits to beneficiaries could be worthwhile.
Ideas for avoiding inheritance tax using pensions
There are many possibilities to use pensions during your lifetime in an attempt to avoid inheritance tax. As with most inheritance tax planning, there is not a single solution that works for everyone. There are always trade-offs and compromises.
Fundamentally, inheritance planning has not changed but it is more likely that your estate’s liability will increase, meaning this could become a greater focus.
The main ways to mitigate against inheritance tax remain as set out below.
Do nothing
It is perfectly reasonable to do nothing in relation to your inheritance tax liability, even if your pension plans increase the cost to your estate. The advantage is that you get to use your pension assets during your lifetime, giving you more control and flexibility in later life. This is a valuable position for many people, who do not want to restrict their access to capital. this means you can spend more and would have the ability to pay for nursing care.
Spend more
You can spend more on your lifestyle during retirement. You get to use the income for your own lifestyle and the additional spending should mean lower inheritance tax against your pension plans, given that the capital would reduce. The disadvantage is that you are likely to pay additional income tax during your lifetime.
Gifts
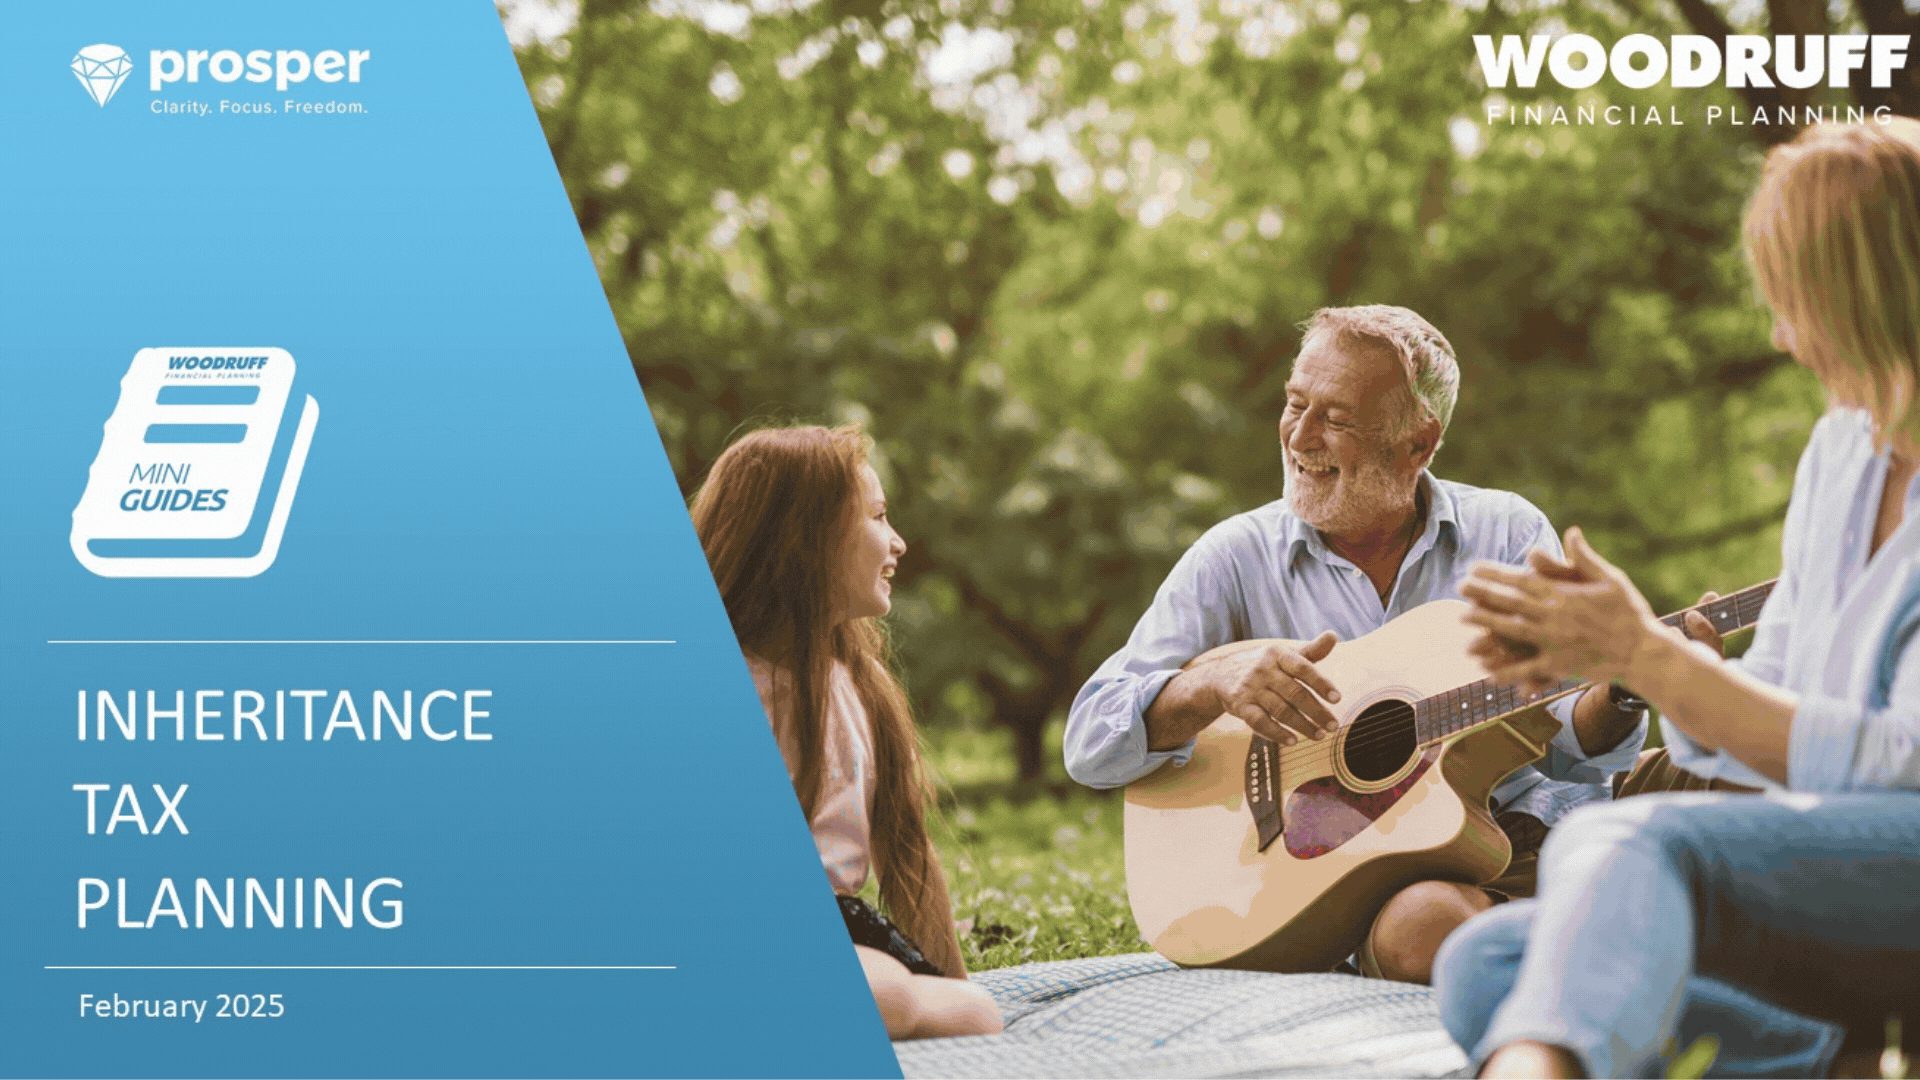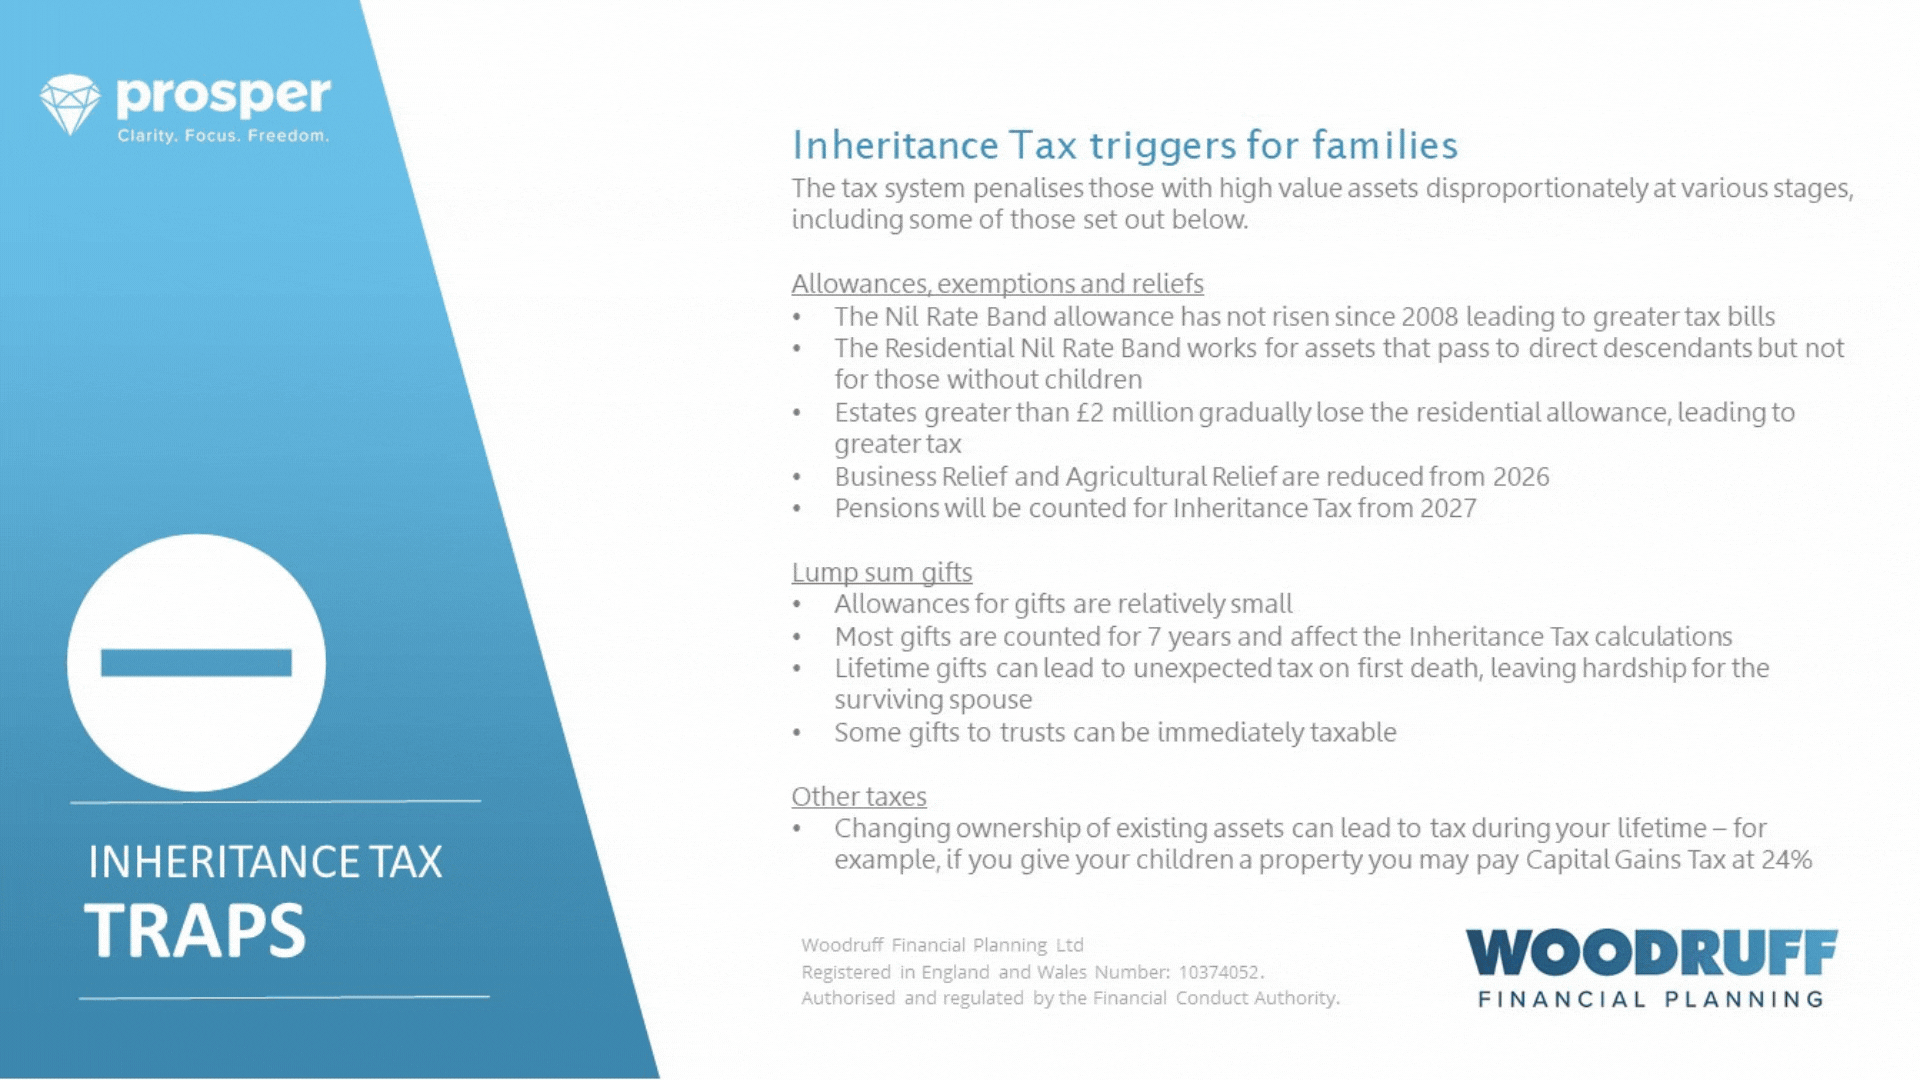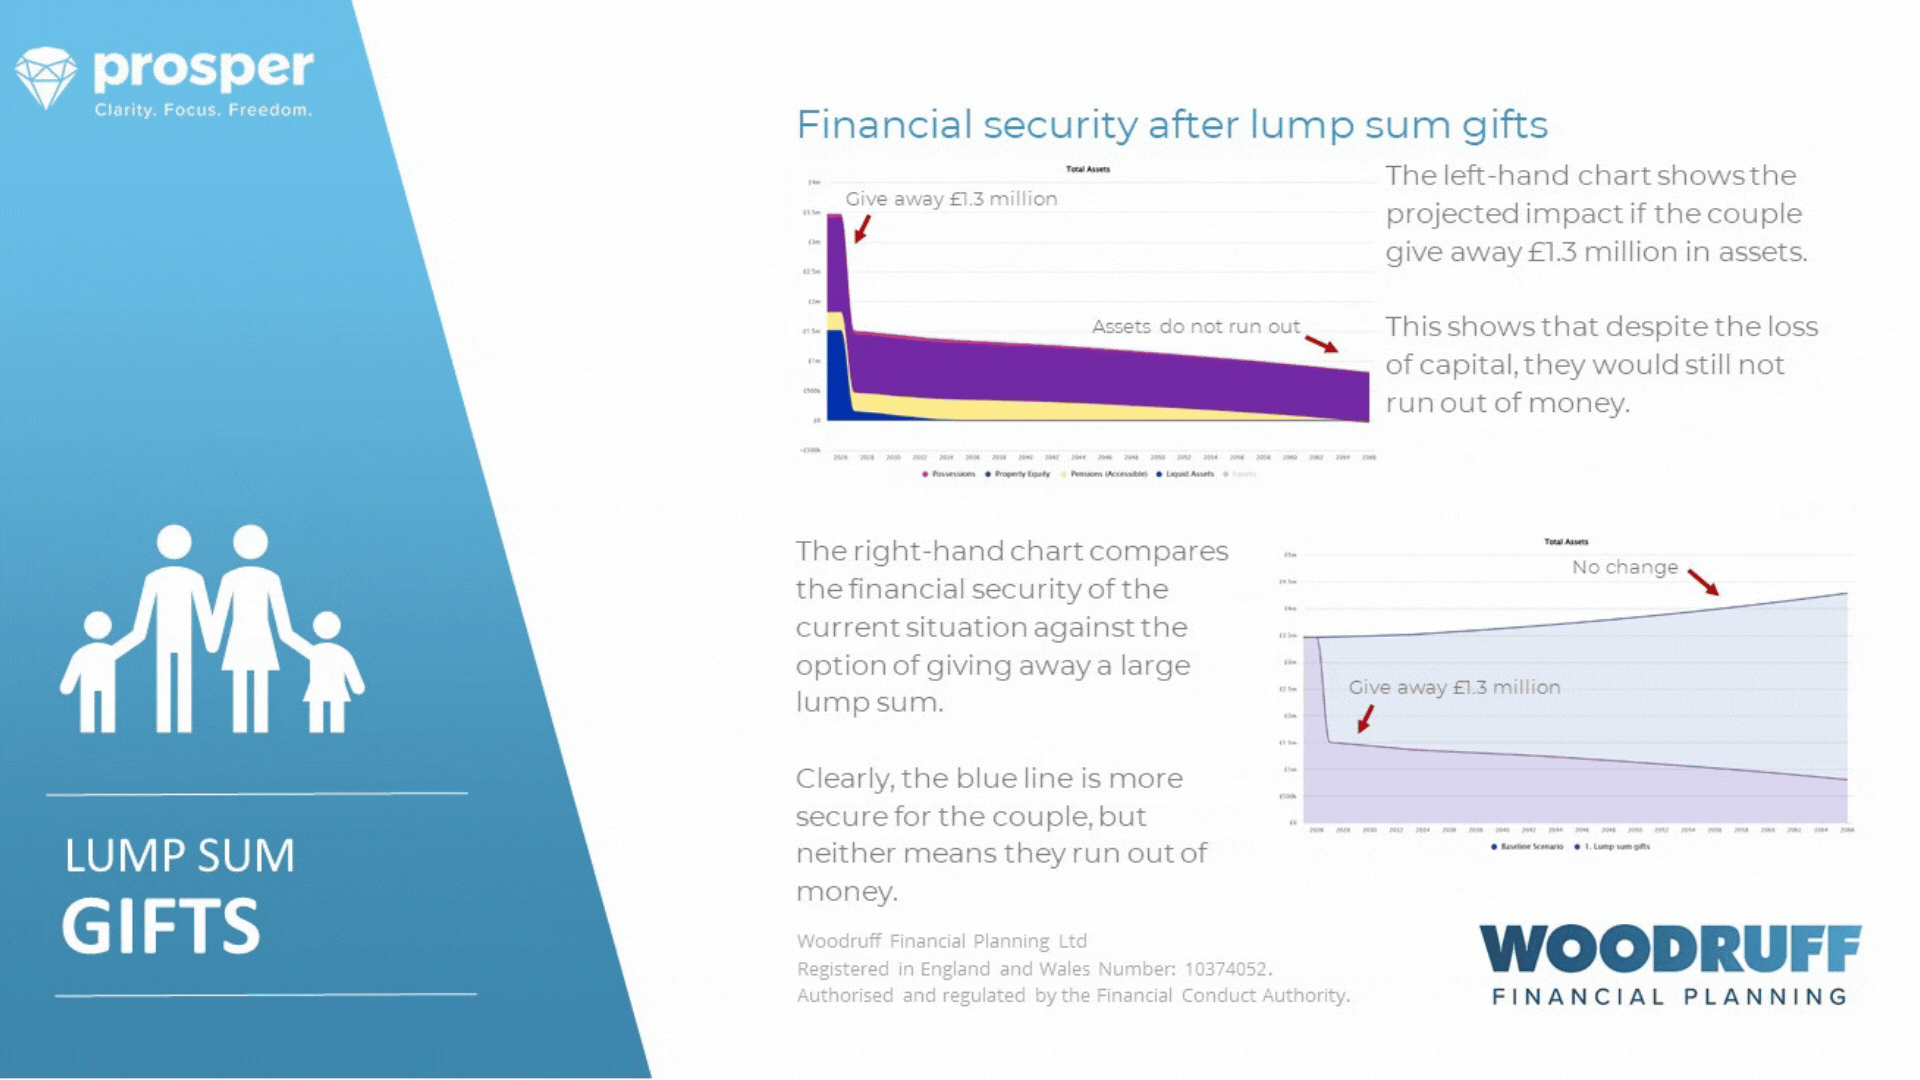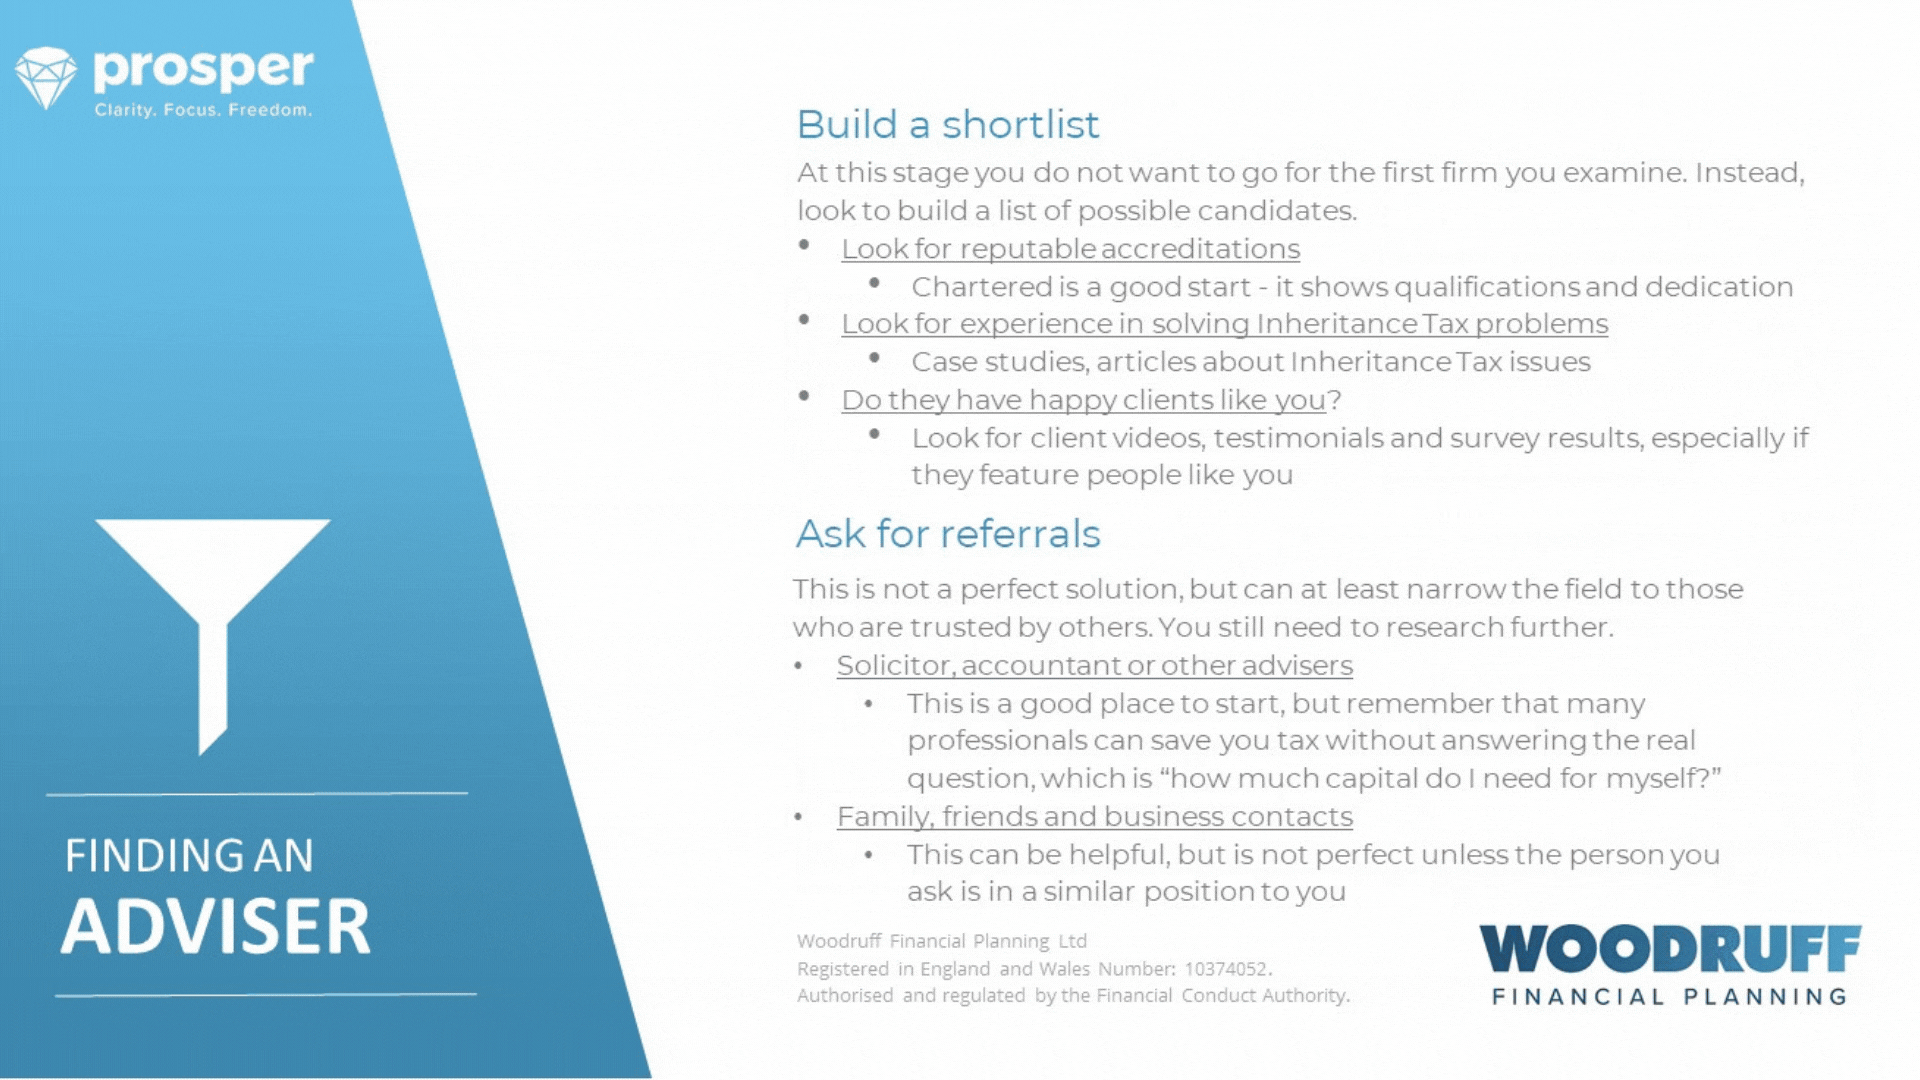
An important method to reduce the value of your estate is to make lifetime gifts out of capital. You can use your pensions for this purpose, but you may have to pay income tax on these gifts as well as surviving for 7 years to make this effective for inheritance tax. Other assets may be more effective for this purpose than the pensions, since they may cost you less in tax to extract money than the income tax due on the pensions.
Gifts out of income from your pensions
You can give away excess income for regular gifts and this is usually free of inheritance tax. If you have paid income tax, the regular gifts are not usually counted for inheritance tax. The downside is that you have to pay income tax, possibly as high as the inheritance tax you seek to avoid.
This may be a sensible option if your income tax rate is lower than the beneficiary’s income tax rate. For example, if the pension member pays income tax at 20% but the beneficiary pays income tax at 40%, it could be better for the member to pay tax, rather than waiting for the beneficiary to pay tax at a greater rate after death of the member.
Imagine this scenario:
- Pension fund worth £400,000
- Member with taxable income of £20,000, taxed at 20%
- Beneficiary with taxable income, taxed at 40%
The member could withdraw £30,000 per year, paying income tax at 20%, or £6,000 per year. This income could be paid to the beneficiary as a gift out of income (free from inheritance tax). This is almost certainly more tax-efficient in the long run to the ultimate family estate than waiting until death, paying inheritance tax at 40% and then additional income tax at 40%.
Give away the tax-free cash
You could take the tax-free cash from your pension and give this away. This would not cost you any tax at the point of withdrawal, and any gift would be outside of your estate after 7 years. This is better for inheritance tax planning than a taxable withdrawal but the downside is that if you later need income from the pension plans, you will have to pay income tax on these withdrawals.
Using the pension to pay for whole of life cover
You can buy inheritance tax insurance, written in trust, which allows you to pay a lump sum to your beneficiaries after you die, which would pay the inheritance tax due. Your pension plan could pay for this insurance, but the income withdrawn to pay the premiums could attract income tax, effectively increasing the annual cost. Other sources of income could be more tax-efficient.
Spouse nomination
Any transfer of pensions on death following your expression of wishes, which nominates your spouse is exempt from inheritance tax. This is a positive option for the short-term but does postpone the inheritance tax bill to the second death situation. By avoiding inheritance tax, your spouse could still have to pay income tax after death of the member if lump sum death benefits are paid, or income is taxable on death of the member after age 75.
Skipping generations
If you nominate your spouse to receive pension death benefits, this could pass to multiple family members in a number of transactions. This could result in inheritance tax being paid a number of times. A solution could be to skip generations, possibly paying benefits to grandchildren. Ultimately, this does not avoid inheritance tax.
Charity nominations
You can nominate charities to receive your pension death benefits. The death lump sums would be free from inheritance tax.
Retain in successor drawdown
This is a valid option to retain flexibility and tax-efficiency. You can pass death benefits to your nominated beneficiaries, and retain tax-free growth and possibly tax-free income on death of the member before age 75. This approach does not avoid inheritance tax, but could be open to you if other assets could be better used for inheritance tax planning, or values are within the available limits for inheritance tax.
Joint life annuities
If you convert your pensions to an annuity with survivor benefits, this would not attract inheritance tax on death of the member. This has a positive inheritance tax position, especially for unmarried couples. the downside is that you would probably lose flexibility of income during your lifetime, and pay income tax. Setting up annuities could mean assets reduce to below the limit for the residential nil rate band, which would have an immediate impact.
In addition, an annuity could be used to pay for whole of life cover, used to fund the capital needed to pay for your inheritance tax due. However, this is a dangerous method as legislation rules out this as it would be classed as tax-avoidance.
8. Review your inheritance tax planning
If you have made it this far, you probably feel you have a potential problems regarding pensions and inheritance tax. Clearly, there are solutions to avoiding inheritance tax, but these are not limited to dealing with your pensions alone. The best approach is to evaluate your current inheritance tax position. If you can establish what you need for your own security, you can then assess whether options exist to avoid inheritance, using pensions or other assets.
Contact us about your pensions and inheritance tax planning, or complete the form below to download our free mini guide to inheritance tax planning.
The UK Government wants to take up to 40% of your money when you die
You can pass on Hundreds of Thousands of Pounds more to your family with careful planning
This FREE Mini Guide will show you how to legally avoid inheritance tax without sacrificing your own financial security.
Want to avoid inheritance tax?
Fill out the form below
By submitting the form above, you agree to our website terms and privacy policy.
We'll also send additional relevant updates on financial planning and investment management. You can unsubscribe at any time.
Got a Question? Call 01206 919101
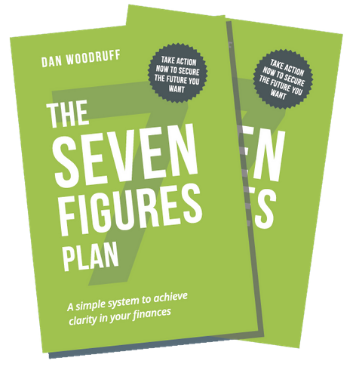
Do you require a simple system to achieve clarity in your finances?
Focus on the 7 most important figures necessary to create your own basic financial plan.
Discover a straightforward way to eliminate the clutter in your financial life to gain clarity on what is actually important with your money.
Author name: Dan Woodruff FCSI CFP
Certified Financial Planner & Chartered Wealth Manager at Woodruff Financial Planning
Dan Woodruff is a Fellow of the Chartered Institute of Securities and Investment (CISI) and winner of the David Norton Award from the CISI. He is a Certified Financial Planner and Chartered Wealth Manager. He is the author of the financial planning book, the 7 Figures Plan. He is a regular contributor to financial contributions and appears on BBC Essex to discuss money matters. He founded Woodruff Financial Planning to provide independent, specialist advice to business owners and high income professionals in Essex and beyond. See his profile page.